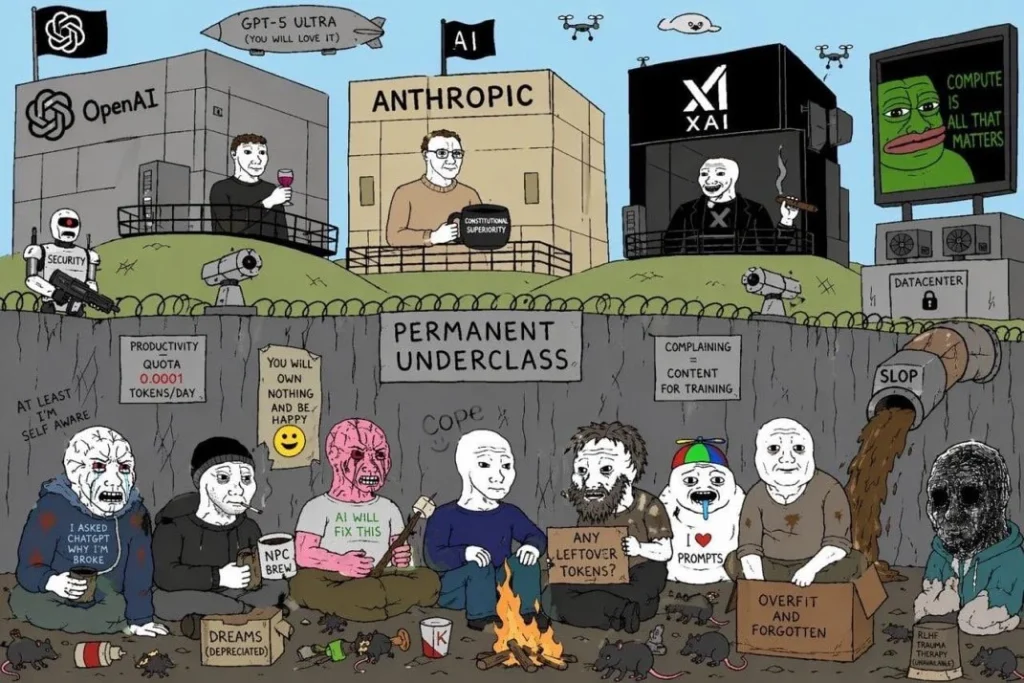
The P/E ratio is all well and good. The question is how reliable those earnings expectations are—and how long today’s profit margins can last. I’m skeptical about AI stocks because training the models costs a fortune, competitors catch up quickly, and customers have more choices. A company can spend billions getting ahead only to discover that someone else can offer something good enough for much less.
Parts of this remind me of solar panels. The market grew enormously, prices collapsed, and plenty of companies that expected to make a fortune went bankrupt. Solar power kept expanding anyway. A technology can succeed spectacularly while its investors lose their shirts. That distinction tends to get lost when everyone is talking about how big the market will become.
There is also the question of where AI will run. I suspect more everyday tasks will eventually be handled by local models on computers, phones, or company servers. You don’t need a giant model in a distant data center—and another monthly subscription—for every job. Some tasks will still justify it. Others won’t. Lower costs could encourage much more usage, but they also raise the question of how much customers will pay for capabilities that become increasingly common.
I’m not convinced that AI will naturally become a winner-take-all business. Google’s position in search is often treated as the template, but why should AI follow the same path? For many tasks, choosing an AI service could end up looking more like choosing a flight-booking site: people use whatever gives them the best result at an acceptable price. Businesses will have switching costs, integrations, and data-security requirements, so it won’t be quite that simple. Still, there is plenty of room for competition.
Web hosting might be another useful comparison: a huge market with large providers, smaller specialists, and constant pressure on prices. There is money to be made. That doesn’t mean every provider gets to keep extraordinary margins.
The situation could change if someone develops an AI system so far ahead of the rest that it can independently drive major advances in research and engineering. It wouldn’t need consciousness to have enormous economic and strategic value. At that point, the argument that AI is the Manhattan Project of the 21st century becomes more plausible. Governments might decide that getting there before China justifies throwing almost unlimited resources at it. Whether that would be a good deal for shareholders is another question. National priorities and investment returns don’t always line up.
Nvidia has an additional problem: its biggest customers have every reason to develop alternatives to its hardware. Google’s TPUs and Amazon’s Trainium show why this matters. If you operate at that scale, reducing the cost of running models is worth a considerable investment. So is reducing your dependence on one supplier.
Nvidia’s advantage is substantial. CUDA, its software libraries, networking, and the experience developers have with its products all make switching harder. A competing chip doesn’t become a practical replacement just because a benchmark looks impressive. But competitors don’t have to beat Nvidia at everything. They only need to handle enough valuable workloads at a lower total cost. Nvidia could remain the technical leader and still face pressure on prices and margins.
That is the risk I find most interesting: AI keeps growing, Nvidia keeps selling chips, and the business still turns out to be less profitable than investors expected. The technology doesn’t have to fail for the investment to disappoint.
Looking at the largest companies over several decades is a useful exercise here. IBM once looked almost untouchable. Oil companies dominated the rankings. General Electric was a model that other businesses were supposed to follow. Kodak was everywhere. The names at the top change, even when their dominance seems obvious at the time.
That isn’t proof that today’s leaders are about to collapse. Nor does slipping down a market-cap ranking necessarily make a company a bad investment. Dividends matter. Spin-offs matter. A business can reward shareholders while other companies grow faster. But it is a reminder of how easily we turn today’s dominance into an assumption about the next twenty years.
I can see AI becoming enormously useful and widely adopted. I can also see fierce competition, falling prices, expensive infrastructure, and customers who are happy to switch when a better deal comes along. Before buying an AI stock, I’d want to know what protects its profits when the technology gets cheaper and more widely available. A growing market alone doesn’t answer that.